
Journal of Social Systems and Policy Analysis | Volume 3, Issue 4: 184-193, 2026 | DOI: 10.62762/JSSPA.2025.210231
Abstract
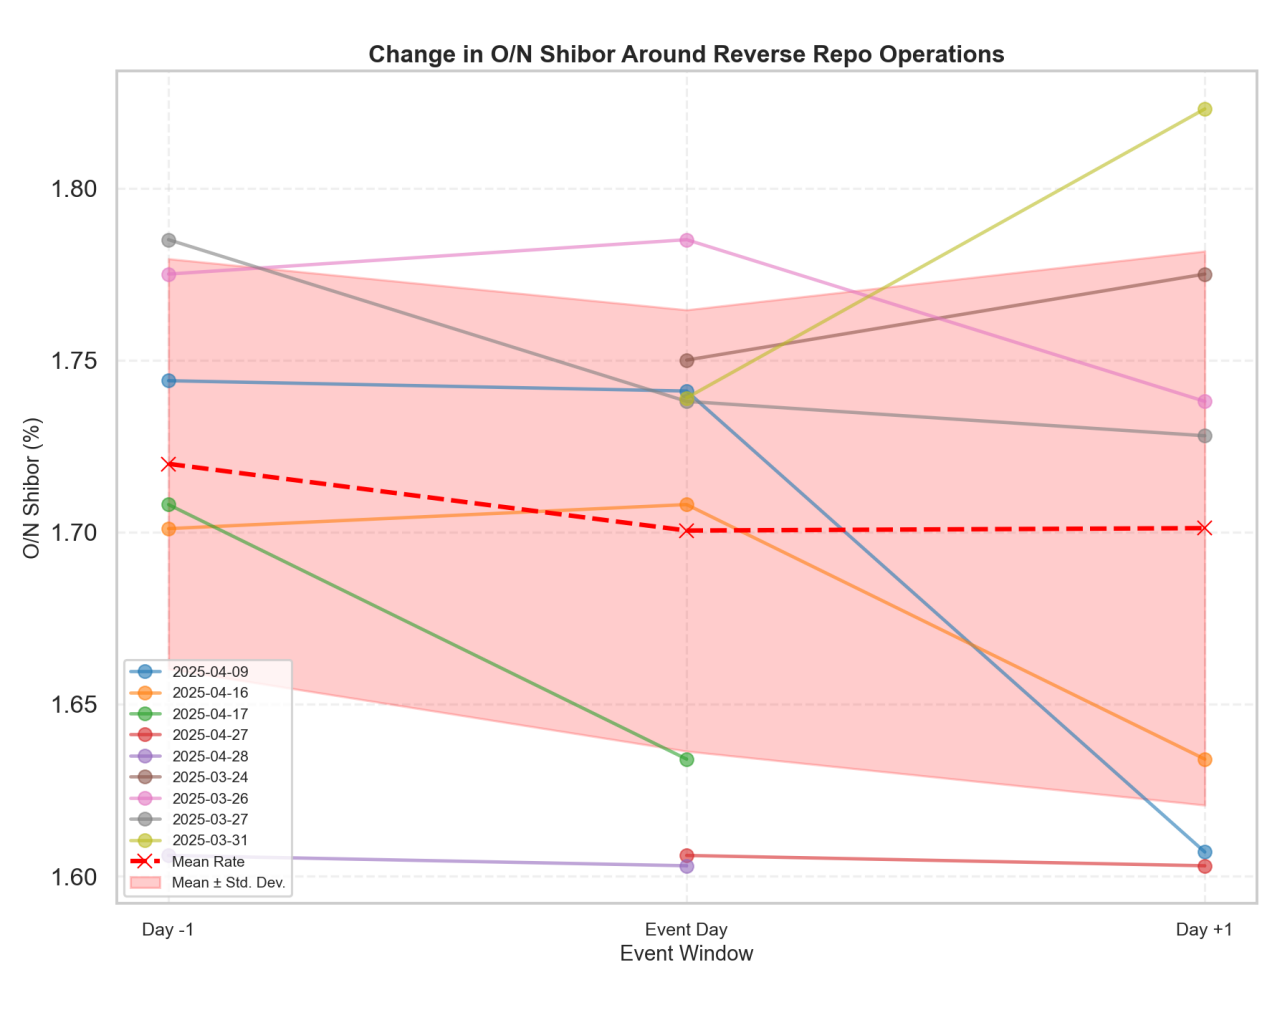
Based on daily data from China's money market between March and April 2025, this study investigates the short-term effects of the People's Bank of China's (PBC) reverse repo operations on the overnight interbank rate (O/N Shibor). Using Ordinary Least Squares (OLS) regression and an event-study approach, the analysis explores both the quantity-based and price-based transmission mechanisms of monetary policy. Empirical results indicate that an increase in the reverse repo amount significantly reduces the overnight rate at the 5% level, confirming the liquidity-supply channel of quantitative policy and demonstrating that liquidity injections effectively ease short-term funding costs. The rever... More >
Graphical Abstract